HELOC vs. Standalone Second Mortgage
A side-by-side of the two products: payment behavior, flexibility, and which strategy each one serves best.
Lessons
Short videos and quick reads on investor HELOCs, standalone second mortgages and blended-rate math.
Revolving line
A credit line behind your existing first mortgage. Draw, repay and redraw — interest only on what you use.
A side-by-side of the two products: payment behavior, flexibility, and which strategy each one serves best.
Your line opens with a set limit. You draw only what a deal needs, and interest accrues only on the drawn balance.
Pay principal down and that availability comes back — reuse it for the next rehab or acquisition without a new file.
Prime is the index, not your rate. Your HELOC rate is prime plus an investor margin set at desk review from your FICO, CLTV, track and line size.
The margin stays fixed. When prime moves, your rate moves by the same amount — and you only pay interest on what you've drawn.
Full terms — no prepayment penalty, eligible states and first liens — are on the HELOC Rates & Terms page (nonqm2nd.com/investment-property-heloc-rates).
Staged rehabs, BRRRR projects and standby cash for the next opportunity. An undrawn line costs nothing each month.
If you know the exact amount and want a fixed payment, a standalone second mortgage is usually the better fit.
Fixed lump sum
One lump sum from $50,000 to $1,000,000, wired at closing, with your first mortgage left untouched.
The fundamentals: a standalone 2nd lien behind your existing first mortgage — no refinance, no tax returns, no origination or broker fees.
How rental cash flow (DSCR) and 12-month bank statement qualifying differ, and how to pick the track that maximizes your cash-out.
How combined loan-to-value caps differ by track — 75% on bank statement, 70% on DSCR, 65% above $500,000 — and when a desktop AVM may be available for cash-outs up to $400k.
DSCR files qualify on gross market rent at a 1.10x minimum — no personal DTI. The bank-statement track uses 12 months of deposits with a 50% expense factor.
Investor files need a 700+ FICO. Title can vest in your LLC.
Bank statement: up to 75% CLTV through $500,000. DSCR: up to 70% CLTV through $500,000 with 720+ FICO. Fixed 2nd above $500,000 through $1,000,000: 65% CLTV. HELOC lines go to $750,000 (bank statement, 720+ FICO, 65% CLTV above $500,000); DSCR HELOCs cap at $500,000.
Cash-outs up to $400,000 can often use a desktop AVM instead of a full appraisal.
The math
Why keeping a low-rate first and adding a second lien often costs less than refinancing everything.
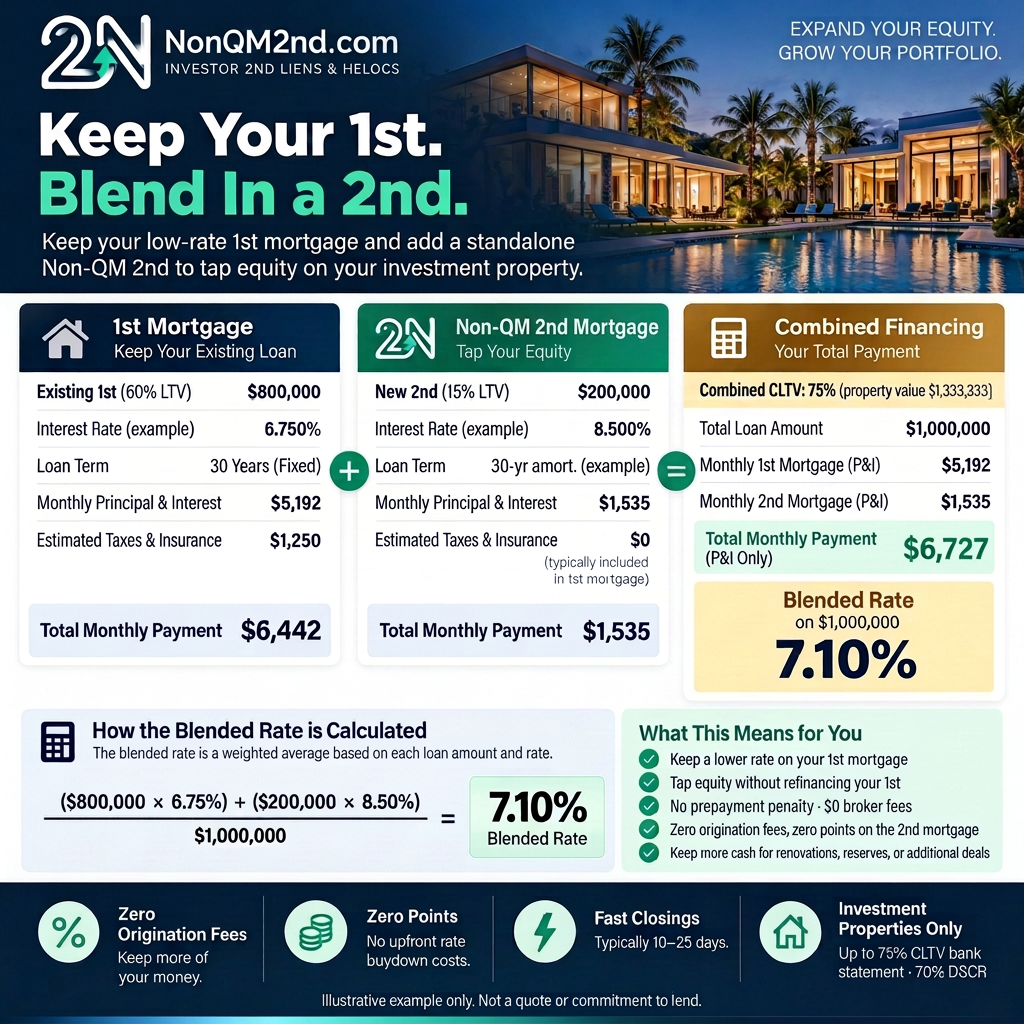
A cash-out refinance reprices your entire balance, not just the new money. Here's the payment math behind keeping your first mortgage and adding a standalone second lien.
It's the weighted average of your two loans: (first balance × first rate + second balance × second rate) ÷ total debt.
Example: $350,000 at 6.75% plus $100,000 at 9.875% blends to about 7.44% — well under an 8.875% cash-out refinance on $450,000.
A cash-out refinance reprices your whole balance, not just the new money. In the example above the refi adds roughly $1,300/mo — about a 15.7% effective cost on the extra $100,000.
Rates here are illustrative. Run your own numbers in the calculator; results are estimates, not a commitment to lend.
Every lesson, both tracks, plus audio overviews.
Open the Academy