Why investors use a second instead of a refinance
Your first mortgage stays untouched
A true standalone second lien. No refinance, no resetting a low first-lien rate, no cash-out on the primary note.
$0 origination & broker fees
No origination points and no broker fee on any file. You pay third-party costs only.
Investor properties only
Rentals and investment properties held personally or in an LLC. We do not do first mortgages or owner-occupied homes.
$50,000 to $1,000,000
Size the draw to the deal — small equity pulls or seven-figure portfolio moves.
Rates rose again. What should investors compare?
See why preserving an existing low-rate first mortgage can matter more when new borrowing costs rise.
The equity decision
Refinance or add a second? Run the numbers
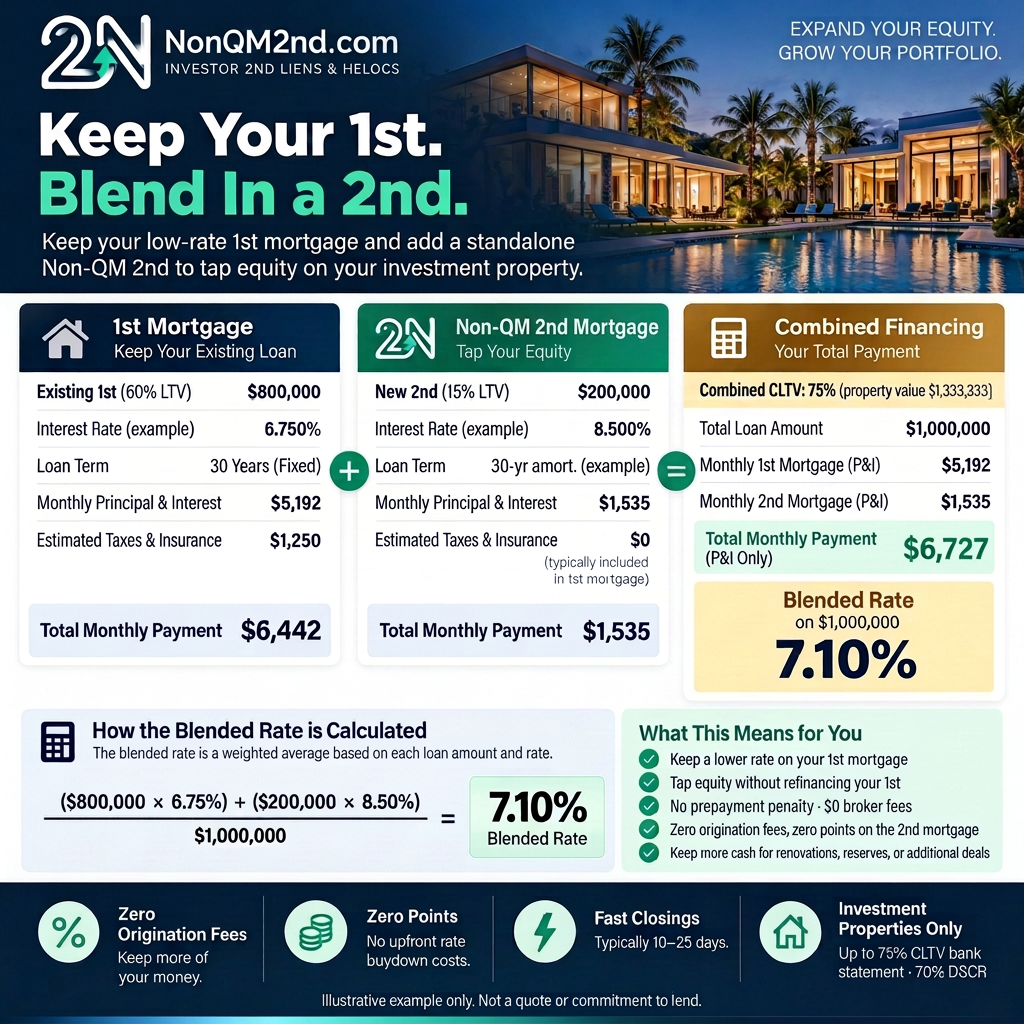
Compare a full cash-out refinance against keeping your first mortgage and adding a standalone second — adjust any figure to match your property.
Enter the rate on your existing first mortgage
Replace with a desk-reviewed rate when available
Replace with a comparable investor refinance quote
75% applies only to bank-statement files with 720+ FICO; 70% applies to DSCR and 700–719 bank-statement files. Qualification requires desk review.
Traditional cash-out refinance
Replace the existing first mortgage
- Consolidated balance
- $450,000 at 7.375% P&I
- New monthly debt service
- $3,108/mo
- Added cost for the cash
- +$1,229/mo
Forfeits your locked first-lien rate, resets amortization to day one, and often carries points and fees on the entire $450,000 balance.
Preserved 1st + standalone 2nd
Keep your low rate
- Liens
- $350,000 at 5.000% + $100,000 at 9.875% IO
- Total combined monthly payment
- $2,702/mo
- Effective blended rate
- 6.08%
Monthly cash flow saved: +$406/mo ($4,875/year)
Refinancing costs you $1,229/mo more to get $100,000 — like paying about 14.7% on that new money.
Blended-rate discount vs. refinancing: 1.29 pts
Illustrative rates — not a quote, approval or savings claim. Payments are principal & interest on 30-year amortization for first liens and interest-only on the second; taxes and insurance excluded. Pricing is set at lock and subject to full underwriting.
Underwriting rules
The same guideline matrix the calculator runs on. Meet one of the two income tracks and stay inside your CLTV band.
Combined loan-to-value
- Bank statement: up to 75% CLTV at 720+ FICO through $500,000
- Bank statement: up to 70% CLTV at 700–719 FICO through $500,000
- DSCR: up to 70% CLTV at 720+ FICO through $500,000
- Either track: up to 65% CLTV from $500,001 to $1,000,000
DSCR rental track
- 1.10x minimum coverage on gross market rent
- 720+ FICO required
- 70% CLTV maximum through $500,000
- No tax returns and no personal DTI calculation
12-month bank statement track
- 700 minimum FICO
- Personal or business deposits, 12 months
- 50% expense factor on business accounts, 0% on personal
- DTI capped at 50%
Property & structure
- Investment and rental properties only
- Personal name or LLC vesting accepted
- AVM valuation where eligible
- Interest-only payments during the 5-year draw period
Guidelines are summarized for estimating and subject to full underwriting, valuation and index pricing at lock. Not a commitment to lend.
Submit scenario
Send your property value, first-lien balance, credit tier and income basis. You get sizing and a next step back — no credit pull to start, and no fees to find out.
- Same-day sizing on most files
- No origination or broker fees
- LLC vesting welcome
- AVM valuation where eligible
Second mortgage questions
More answers on the second mortgage FAQ, the investment property HELOC guide and the Investor Academy.